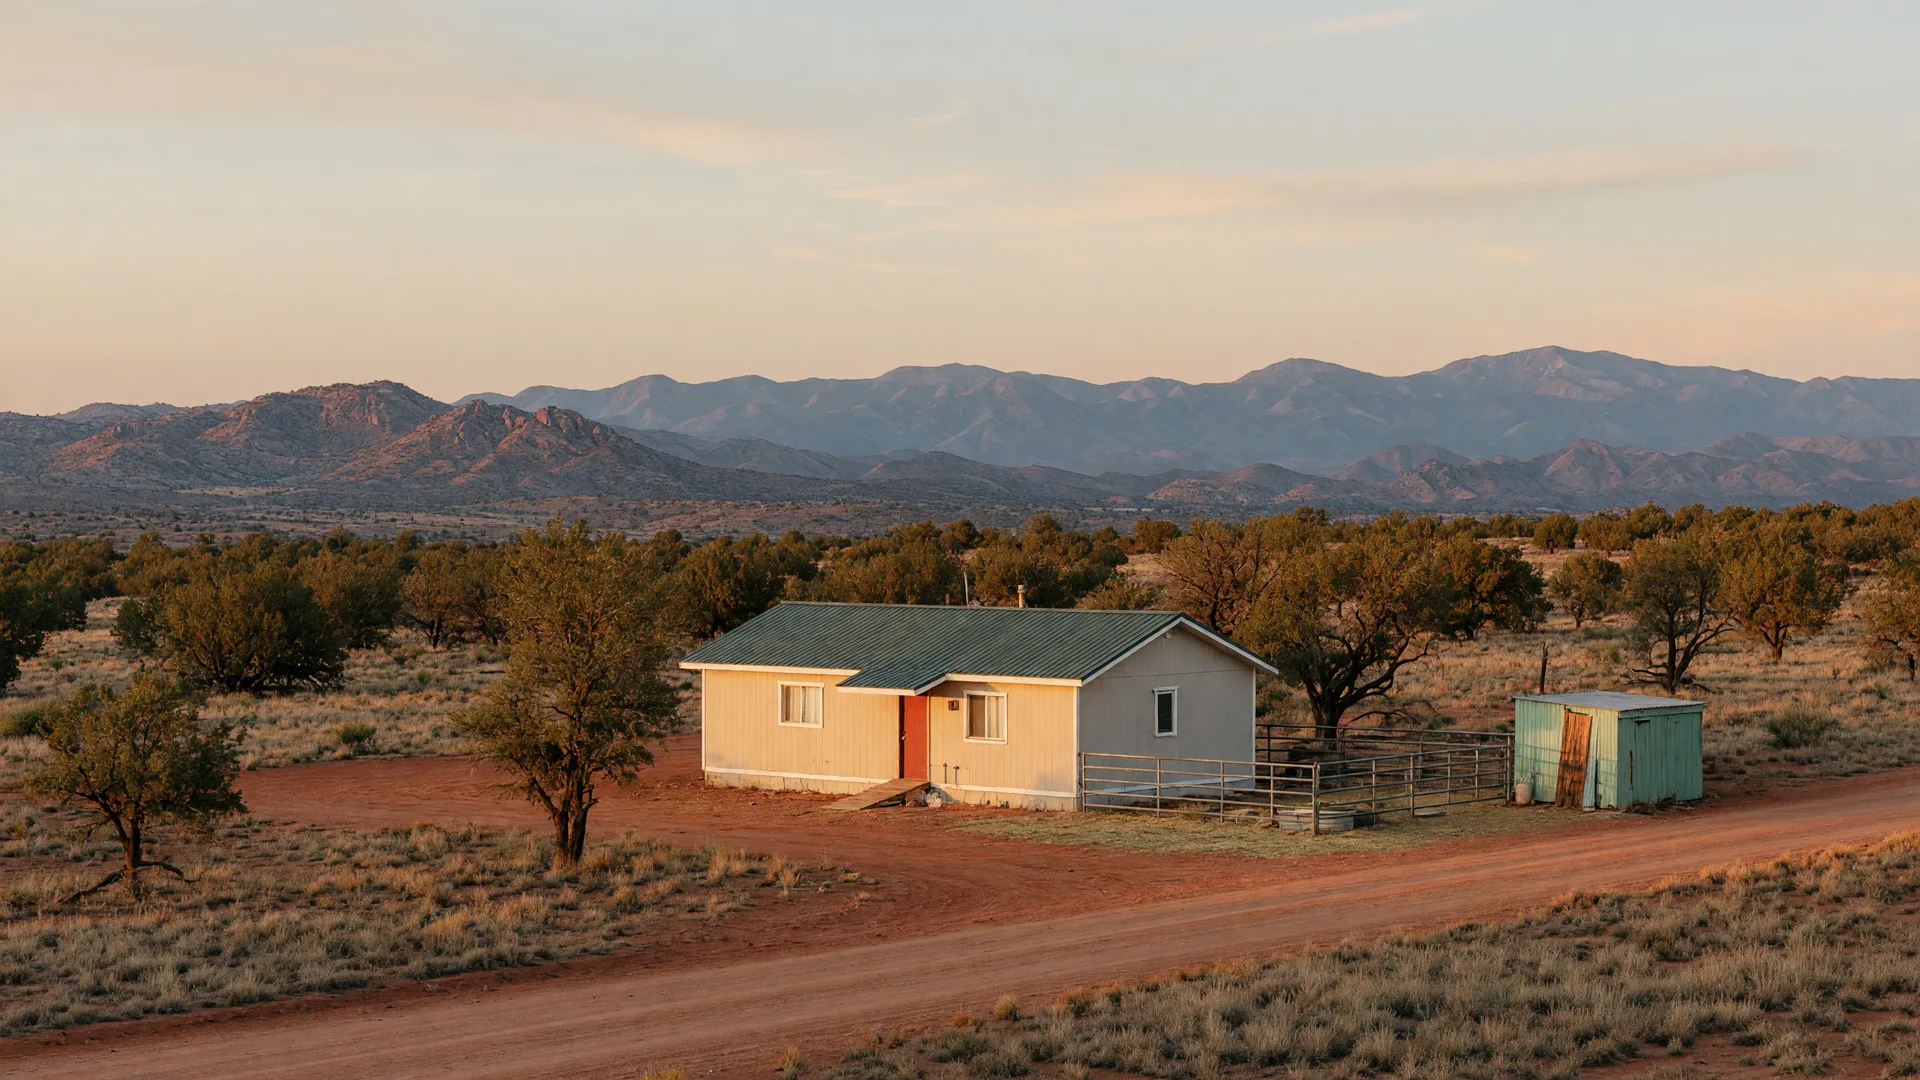
Can you get a normal mortgage on a manufactured home in Gila County, or do you have to pay cash? The honest answer is that you can finance a manufactured home like a site-built house, but only after one legal step happens: the home has to be converted from personal property to real property with an Affidavit of Affixture. Until that document is recorded with the county recorder, the home is titled like a vehicle through the Arizona MVD, and most lenders will not touch it. Here is how the affixture rule works, what it means for FHA, VA, and USDA financing, and what I verify on every manufactured-home-on-acreage property I represent.
Financing and affixture facts in this guide come from the Arizona Revised Statutes (A.R.S. § 42-15203), HUD's manufactured home lending requirements, and the Gila County Building Safety division.
THE SHORT ANSWER: YES, ONCE IT IS REAL PROPERTY
The first thing to understand is the legal status of the home itself. In Arizona, a HUD-code manufactured home, meaning one built on or after June 15, 1976, can be financed like a site-built home, but only once it has been converted from personal property to real property. Until that conversion happens, the home is titled through the Arizona MVD the way a vehicle is, and a lender treats it as chattel. That means a personal-property loan with higher rates and shorter terms, or no loan at all, which is why so many off-grid buyers assume these properties are cash-only.
The conversion is done with a single document: the Affidavit of Affixture. This is the most important piece of paper in manufactured-home real estate, and it is the first thing I ask about when a buyer calls about a manufactured home on acreage.
THE AFFIDAVIT OF AFFIXTURE: THE ONE DOCUMENT THAT CHANGES EVERYTHING
Under Arizona law (A.R.S. § 42-15203), someone who owns both the manufactured home and the land it sits on can file an Affidavit of Affixture with the county recorder where the property is located. The form is ADOT/MVD DOR 82528, and it lists the home's VINs and any security interests that are not being terminated. Once it is recorded, three things happen:
- The MVD title is surrendered and cancelled, and the home becomes part of the real estate parcel.
- The county assessor moves the home from the personal-property roll (the M account) to the real-property roll (the R account), and personal-property tax is eliminated in favor of real-estate taxation.
- The home can now be sold and financed like a site-built home, which is exactly what FHA, VA, USDA, and most conventional lenders require.
There is one physical requirement behind all of it: the home has to be permanently affixed. That means a permanent foundation built to HUD's Permanent Foundations Guide, with the wheels, axles, and towing gear removed. A home sitting on blocks with its wheels still under it is not affixed, no matter what the paperwork says.
WHAT GILA COUNTY REQUIRES BEFORE YOU GET THERE
The affixture rule is state law, but Gila County adds its own requirements on top of it, and they matter if you are buying or selling out here. Since March 22, 2007, only HUD-approved manufactured homes have been permitted in unincorporated Gila County, so a pre-1976 mobile home is effectively out of the picture for a new placement. The county is under contract with the Arizona Department of Housing's Manufactured Housing Division to permit and inspect these homes, and a Manufactured Home Permit covers the required setup inspections.
The county's zoning ordinance treats a manufactured or modular home as one permitted single-family dwelling on any lot that meets the minimum size for its density district, which is good news for buyers of rural acreage. The home itself has to contain more than 720 square feet of living space, and it has to be placed on a permanent foundation or permanent piers, with skirting required when it sits on piers. I walk through the districts and what they allow in my Gila County zoning guide, because the district on your parcel controls the lot size, setbacks, and what else you can do with the land.
And in rural Gila County there is no sewer hookup waiting for you, so an approved septic system is part of the package. The county's Wastewater Department issues the septic permit, and there is a transfer-of-ownership inspection required before a property served by a septic system can be sold. That inspection is a real gate in the transaction, not a formality, and it is one of the reasons I verify the septic story before a buyer ever writes an offer. If you are looking at a parcel and wondering whether the water and waste systems will pass, my water access guide covers the well side of that same due diligence.
YOUR FINANCING OPTIONS ONCE THE HOME IS AFFIXED
Once the Affidavit of Affixture is recorded and the home is real property, the financing world opens up. Here is what the main programs actually require:
- FHA Title II: the home must be classified as real property on land owned by the borrower, sit on a permanent foundation built to FHA criteria, be at least 400 square feet, be built after June 15, 1976 with a HUD certification label, and stay on a permanent chassis. Terms run up to 30 years, and down payments can be as low as 3.5% with a 580+ credit score.
- VA loans: eligible veterans and active-duty buyers can finance with 0% down, with a funding fee roughly between 2.15% and 3.3%. The home needs its HUD label and data plate, must be permanently affixed to a foundation meeting HUD and local codes with wheels and towing hardware removed, must be real property on owned land, and must pass a VA appraisal. It also has to be your primary residence.
- USDA Rural Development: 0% down in qualifying rural areas, and much of Arizona outside metro Phoenix and Tucson qualifies. The home must be real property with the affidavit recorded, and it must meet USDA installation and foundation requirements, typically on a 30-year fixed term.
Conventional loans work too once the home is affixed, which is why the affixture status is the hinge the whole deal swings on. A buyer with a VA or USDA approval in hand can be a very strong offer on a rural property, and that is a real advantage when you are competing for acreage that most buyers cannot finance at all.
"Can I get a normal mortgage on a manufactured home, or do I need to pay cash?" is one of the first questions I hear from off-grid buyers. The answer is usually yes, you can finance it, but only if the affixture paperwork is real and recorded. That is checkable before you ever make an offer.
WHY LENDERS BAIL ON UNAFFIXED HOMES
Most of the financing pain I see in this market is not about the buyer's credit. It is about the property's status. A lender sees an unaffixed manufactured home and the loan does not fit the box, so it gets rejected or delayed late in the process, often after the buyer is already emotionally invested. Add an off-grid well and septic to the picture and the underwriting gets even more careful, because the lender needs the water and waste systems verified too.
The fix is to check the status before you offer, not after. Ask whether the Affidavit of Affixture is recorded, ask to see it, and confirm the home is on a permanent foundation with the wheels and axles gone. Then verify the well and septic story the same way. That is the due diligence I run on every manufactured-home listing I represent, and it is exactly why I am based in Globe rather than Phoenix: I know which parcels have their paperwork in order and which ones are going to stall a loan. You can read more about my background and how I work on my About page.
WHAT THIS MEANS FOR BUYERS AND SELLERS
For buyers, the takeaway is simple: an affixed manufactured home on acreage is a financeable property, and that changes how you should compare it to a cash-only parcel. For sellers, it is just as important. An affixed home sells to the whole pool of FHA, VA, USDA, and conventional buyers, while an unaffixed home narrows the market to cash buyers and chattel loans, which usually means a lower price and a longer time on market. If you own a manufactured home on land and the affidavit was never recorded, that paperwork is one of the highest-value fixes you can make before listing, and it is cheap compared to a stalled sale.
This is also why I check the affixture status, the zoning, the well, and the septic on every property before I talk price. You can see how I present a property when that homework is done on my current listings page, where every listing comes with the water, zoning, and access story verified, not just an MLS sheet repeated back at you.
THE BOTTOM LINE
You can finance a manufactured home in Gila County, but the financing only works when the home is real property. Confirm the Affidavit of Affixture is recorded, confirm the home is permanently affixed on a foundation with the wheels and axles removed, and then match the property to the right program, FHA, VA, USDA, or conventional. Do that and a manufactured home on acreage stops being a cash-only curiosity and becomes a perfectly normal, financeable piece of rural real estate.
If you are looking at a manufactured home on acreage and wondering whether it can actually be financed, call or text me at 480-797-1824, or send a message through the contact page. I will pull the affixture status, the zoning, and the well and septic story with you so you can make an offer with your eyes open.
Written by Neil Blindauer
Realtor, DeLex Realty · A.I. Certified Agent™
With 9 years in real estate, I specialize in off-grid land, rural homesteads, and one-of-a-kind properties across Gila County, serving Globe, Miami, Winkelman and Kearny.
Learn more about Neil